Start with spending, not capital
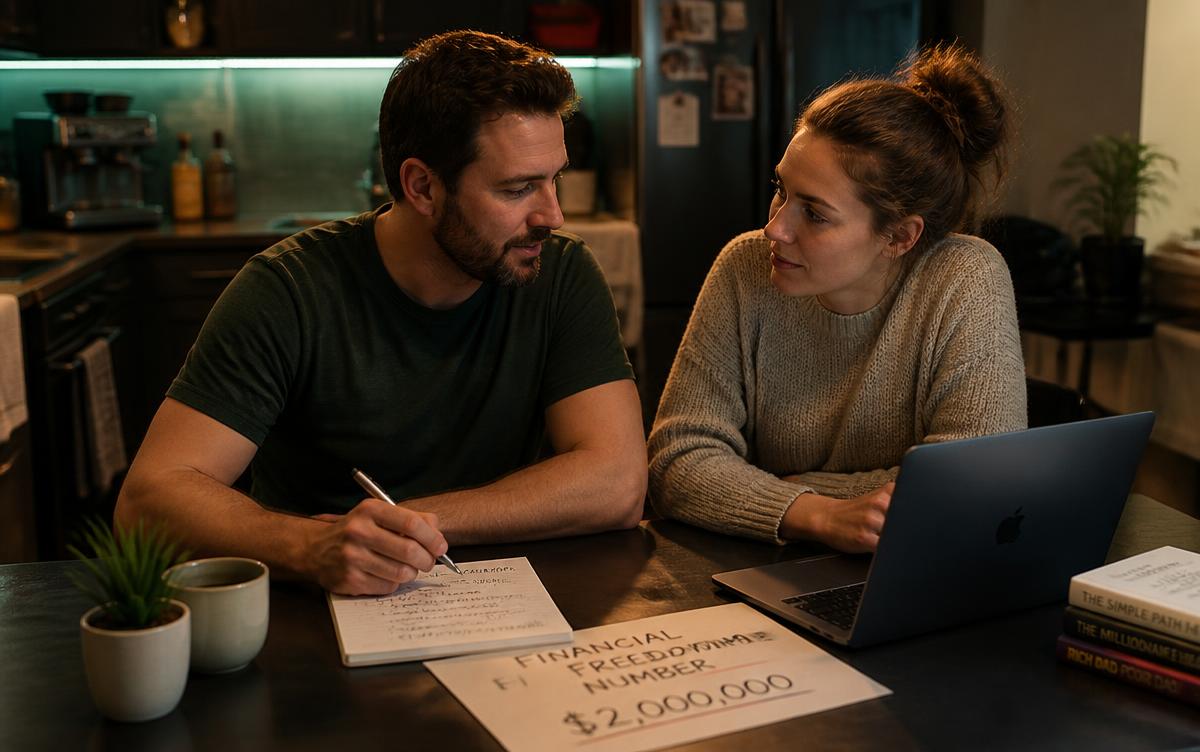
The number is not chosen, it is derived. First you define the annual spending of the life you want — including health, taxes, housing and the treats you will not drop — and only then compute the capital needed. Doing it backwards produces round, meaningless figures like 'a million'.
A change of city can shift that spending 40% in either direction, and with it your entire number. So compute at least two scenarios: life where you are and life where you would like to be.
“The safe withdrawal rate isn't a promise: it's a margin of safety that lets you sleep for thirty years.”
The withdrawal rate is not a law of physics
The classic 4% comes from a US study with 30-year horizons. If you retire at 45 with 50 years ahead, or live outside the dollar, 3.25-3.5% is more prudent. Every quarter point you lower adds years of capital, but also years of work.
The alternative to a rigid percentage is a flexible rule: withdraw between 3% and 4.5% depending on how markets go, with a 10% cap on discretionary spending cuts. Flexibility is worth more than any portfolio optimisation.
The 4% rule: number = annual spending × 25.
Sequence of returns: the first five years' risk
Two people with the same average return end up in different places if one hits a bear market early. Selling cheap shares to live on in year one leaves a hole later good runs never fill.
The defence is simple: two or three years of spending in stable assets, willingness to cut 10% in bad years and, if possible, some small income during the early years. Not glamorous, but it is what makes the plan robust.
“Your time to retirement depends on one variable only: the percentage of your income that you save.”
Taxes and country: the discount almost nobody applies
Your number is not measured in gross capital but in net available spending. If you withdraw €40,000 and pay 19-23% on the gains within that sale, you need more capital than the 25× rule suggests.
Changing country changes the whole calculation: capital gains tax, private healthcare cost, exchange rate and institutional stability. A number that works in Lisbon may fall short in Zurich and be generous in Medellín.
| Withdrawal rate | Capital needed | Multiple | Comfortable horizon |
|---|---|---|---|
| 4.0% | €1,000,000 | 25× | 30 years |
| 3.5% | €1,142,000 | 28.6× | 40 years |
| 3.25% | €1,230,000 | 30.8× | 45-50 years |
| 3.0% | €1,333,000 | 33.3× | 50+ years |
Your savings rate rules over your return
Going from a 10% to a 30% savings rate cuts more than a decade off the path. Going from 7% to 8% returns cuts a couple of years. The first depends on you; the second on a market you do not control.
And there is a forgotten double effect: every euro you permanently stop spending raises your savings rate and lowers your number at the same time. It is the only lever that pushes both variables the right way.
- Define target spending before target capital.
- Review the number yearly, not with every headline.
- Include health, taxes and possible country changes.
- Keep 2-3 years of spending outside equities.
Starting from zero, with a 5% real annual return.
The milestones before the final number
Financial freedom is not a switch. There are intermediate milestones that already change your life: covering essential spending with passive income, being able to work part-time, or holding enough capital that stopping contributions still gets you there through compounding.
That last milestone — sometimes called coast — usually arrives 10 to 15 years before the full number, and it is when financial stress genuinely drops.
“Controlling your time is the highest dividend money pays.”
Real case: the couple that cut their number by €260,000
Ana and Pablo first calculated their number with a €5,400/mo spend: they needed €1,620,000 at 4%. The figure felt unreachable and they nearly abandoned the plan.
They reviewed fixed costs, moved city within the same country and adjusted car and insurance. Their target spend fell to €4,530/mo and their number to €1,359,000: €261,000 less and seven years earlier. They did not raise income; they changed the base everything is calculated on.
The three numbers: bare-bones, comfortable and ideal
Calculating a single number hides a trap: it forces you to nail the exact lifestyle you will have twenty years from now. It is more useful to work with three chained figures. The bare-bones number covers only the essentials — housing, food, insurance and utilities — with no travel or discretionary leisure; it usually sits between 60% and 70% of your current spending. The comfortable number keeps your present standard of living, with leisure and a trip or two a year. The ideal number adds room for large unexpected costs, helping children or grandchildren, and a retirement with no visible restrictions.
Having all three numbers calculated in parallel changes how you make decisions. If you lose your job or the market drops 30% right before you retire, the bare-bones number tells you what you truly need to avoid being forced back to work. The ideal number, by contrast, is what you use to decide whether it is worth working two more years in exchange for a frictionless retirement. Between the two sits the comfortable number, usually the real target of most financial independence plans.
- Bare-bones: 60-70% of current spending, no discretionary leisure.
- Comfortable: your current spending maintained over time.
- Ideal: current spending plus room for surprises and family.
Geo-arbitrage: adjusting the number by country and cost of living
Geo-arbitrage means earning or accumulating capital in an expensive economy and spending it in a cheaper one, without giving up quality of life. Moving from a capital city to a smaller provincial town can cut housing spend by 30-40%; moving to Portugal, Mexico or Thailand can cut it by 50% or more in some categories, though not all: technology, international flights and certain imported goods do not fall as much as rent does.
Before revising your number downward for a country change, check three things: the real cost of private healthcare or international insurance, the tax treatment of capital gains and pensions in the new country, and exchange-rate stability if your income and capital sit in a different currency from your spending. A number that drops 35% on paper can end up at a real 15% once these three points are covered, and it can still be worth it if the rest of life makes up for it.
Geo-arbitrage also works partially and reversibly: spending six months a year in a low-cost country while keeping tax residency and a home in the expensive one lowers annual spending without giving up the base you already know. It is an intermediate strategy many people use in the first years of financial independence before deciding on a permanent move.
Children, mortgage and private healthcare: the three biggest movers of the number
A child adds between €300 and €700 of monthly recurring spending in the early years, and that figure rises with private education or extracurricular activities. Over 25 years of a child's dependent life, that is an extra capital requirement of roughly €90,000 to €210,000 in your number, depending on whether you plan to cover university or only basic upbringing. It is worth calculating this block separately, with an expiry date, rather than mixing it into the rest of the portfolio's perpetual spending.
The mortgage is the factor most often modelled wrong. If you finish paying it before retiring, your annual spending drops sharply and your number is calculated on that reduced spending; if it is still active when you retire, you must add the remaining instalments as fixed spending with a known end date, rather than treating it as perpetual 25× spending. Confusing the two is the most common calculation error in financial freedom number simulators.
Private healthcare tends to be the most underestimated block. In countries without universal public coverage, a full medical insurance plan for two people over 60 can cost between €4,000 and €9,000 a year, and that cost rises non-linearly with age. In countries with solid public healthcare but long waiting lists, many retirees keep a complementary private policy costing €800 to €1,500 a year. This expense is worth reviewing every five years, because premiums rise faster than general inflation.
Inflation and the yearly update of the number
The financial freedom number is not calculated once and filed away: it is a living figure that must be adjusted each year for real inflation, not the published average. The spending basket of someone with a variable mortgage, school-age children and a car does not move like the general CPI; it is worth calculating your own personal inflation rate from your actual spending categories.
The simplest way to update the number is to review last year's actual spending each January, apply the expected inflation of the categories that weigh most in your budget — housing, energy and food tend to be the most volatile — and multiply that new annual spending by your chosen withdrawal rate. If your number rises 4% but your portfolio grew 9% that year, you are still advancing; if your number rises faster than your portfolio for two years running, it is time to review both spending and savings rate.
Once retired, protection against inflation does not come only from the initial number but from portfolio composition: keeping part of it in assets that historically track inflation — global equities, some commodities or inflation-linked bonds — reduces the risk of your purchasing power eroding over a thirty- or forty-year retirement.
The three levers to get there sooner: savings, returns and income
There are only three levers to shorten the path to your number: raising the savings rate, improving portfolio returns, or increasing income. They do not carry equal weight. Going from a 15% to a 35% savings rate can cut 10 to 15 years off the path; going from an average 6% to 8% return cuts 2-3 years over the same horizon, and with more risk. The savings rate is the only one of the three that depends almost entirely on your own decisions rather than the market.
Raising income is the lever with the greatest long-term reach, but also the slowest to activate: it requires training, a career change or salary negotiation, processes measured in years, not months. Its advantage is that, unlike savings, it has no natural ceiling: you can only cut spending down to a reasonable floor, but you can keep raising income throughout your working life.
The most effective combination is not maximising a single lever, but moving all three moderately at once: a 20% income raise directed entirely to savings boosts the savings rate without touching living standards, and a portfolio diversified a bit more internationally reduces volatility without sacrificing much expected return. These moderate combinations tend to be more sustainable than aggressive bets on a single variable.
- Savings: the fastest lever and fully under your control.
- Returns: marginal improvement, higher associated risk.
- Income: slow to activate, no long-term ceiling.
The number with a state pension or rental income
The 25× rule assumes your entire retirement is funded solely by the portfolio, but few people fit that pure case. If you expect a €900 monthly state pension from age 67, and plan to retire at 50, your real number is the sum of two capitals: one covering full spending until the pension arrives, and a smaller one, calculated on spending minus the pension, for the rest of your life.
Rental income works similarly, but with an important caveat: it is not as stable as a state pension, because it includes vacancies between tenants, repairs and market swings. A reasonable practice is to discount 15% to 25% of expected gross rent before subtracting it from annual spending, so as not to overestimate how much it really reduces your number.
When you combine portfolio, state pension and rental income, the number stops being a single figure and becomes a timeline of overlapping income streams. Modelling it year by year, rather than with a single formula, avoids both overestimating the safety of variable income and underestimating the real relief a state-guaranteed pension provides.
The bridge to retirement: funding the in-between years
Anyone retiring before the legal pension age faces a 'bridge' stretch: the years between the day they stop working and the day the state pension starts. That bridge must be funded with your own capital, and miscalculating it is one of the costliest mistakes in the plan, since it often requires 15 to 20 years of full spending before any guaranteed income arrives.
One way to structure it is to split the capital into two buckets: the bridge bucket, invested somewhat more conservatively because it has a known horizon and usage date, and the long-term bucket, which stays invested more aggressively because it will not be touched for 15 or 20 years. This separation avoids selling equities at a bad time just because you need short-term liquidity.
Other ways to ease the bridge include partial income during the early retirement years — consulting, part-time work or renting out an asset — and the orderly drawdown of savings vehicles with different tax treatment by age, such as pension funds, whose access is usually restricted before a certain age. Planning the order in which you draw from each bucket matters as much as having saved enough in the first place.
The moving-target effect: why the number drifts every time you get a raise
The moving-target effect happens when every pay rise automatically turns into more spending — a bigger house, a newer car, pricier holidays — and the financial freedom number rises at the same pace as income, leaving the independence date permanently just as far away. It is why many high earners do not feel closer to financial freedom than they did ten years ago, despite earning twice as much.
The most effective defence is automating the destination of every raise before it hits the checking account: deciding in advance that a fixed share of any increase — half, for example — goes straight to investment, and only the other half feeds regular spending. That way living standards keep improving, but at a slower pace than income, and the savings rate rises with each promotion instead of staying flat.
It also helps to set the target spending behind the number in absolute terms and review it deliberately, rather than letting it drift upward passively just because you can now afford it. Asking yourself, every time spending rises, whether that increase buys lasting happiness or just temporary status, is the simplest filter to stop lifestyle inflation before it becomes the reason your number never stops growing.
- Automate the destination of every raise before it hits the account.
- Set target spending in absolute terms, not as a floating share of income.
- Question every spending increase: temporary status or lasting improvement?